Ordinary car insurance does not cover a stranger driving your car for money. The moment a learner takes the wheel in a lesson, you need a driving instructor policy, and it is one of the three big fixed costs of the job alongside the car and the cost of finding pupils. This guide covers what it has to include, what it costs, and how to pay less for the same cover.
What the policy has to include
Instructor insurance is sold by specialist brokers rather than the comparison sites, and the policies vary more than ordinary car cover. Check for each of these before comparing prices.
Any learner driving. The core of the policy. Every pupil, with a provisional licence, is covered to drive the car under your instruction. Some policies restrict the age range or exclude previously banned drivers; if you plan to teach either, say so when you quote.
Dual controls and modifications. The controls, the extra mirrors, the roof sign and the livery all need to be declared and covered. An undeclared modification is the classic reason a claim is refused.
Replacement dual-control car. If the car is off the road after an accident, an ordinary courtesy car is useless to you. The good policies supply a dual-control replacement, or pay a daily amount while you hire one. Without it, a two-week repair is two weeks with no income.
Negligent tuition. Covers a claim that your instruction, not the pupil's driving, caused an accident. Rare, but the claims are large.
Public liability. Injury or damage to a third party arising from your business rather than from driving: a pupil trips over your cone, say. Often sold as a separate policy or add-on for £50 to £100; the trade bodies include it with membership.
Off-road and test cover. The car being driven by an examiner-accompanied pupil on test, and on private land for the first lesson. Standard on most policies, worth confirming.
Breakdown with onward travel. Not insurance, but buy it with the policy. A breakdown halfway through a lesson with a pupil in the car is a problem you want solved by one phone call.
What it costs
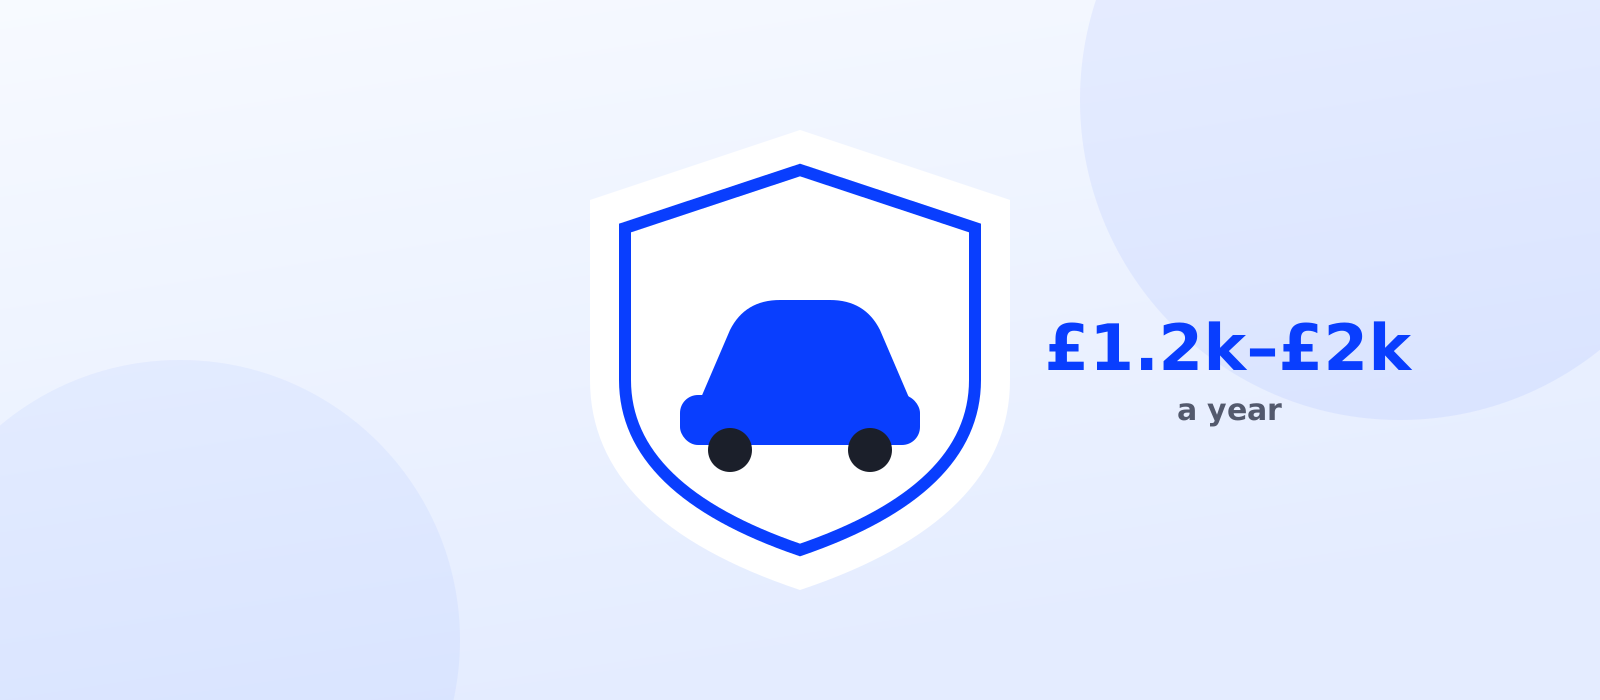
At the time of writing, a full-time ADI with a few years' experience, a clean record and a low-group car is quoted somewhere around £1,200 a year. The same instructor in inner London, or with a newer, higher-group car, is nearer £2,000. Trainees on a pink badge pay more, often a few hundred pounds more, because the insurer has no record of them teaching.
What moves the premium:
- Where you teach. Postcode matters more than for ordinary cover, because the car spends its day in traffic in the same place.
- The car's insurance group. A group 5 to 8 supermini against a group 15 to 20 hatchback can be the difference between £1,200 and £1,800 on its own.
- Your claims and convictions. As with any motor policy, and the insurer will also ask about pupils' accidents in your car.
- Hours taught. Some insurers offer a cheaper part-time rate for instructors teaching under a set number of hours a week. Worth asking if you are starting part time.
- Excess. A higher voluntary excess cuts the premium. Set it at an amount you could pay the week after an accident, not the amount that gives the lowest quote.
If you lease a dual-control car from a driving school or a specialist lessor, check whether insurance is bundled. Several leases at around £180 a week include it, which is why a lease that looks dear next to a £125 one can be cheaper once the policy is added. The sum is in how much driving instructors earn.
Paying less for the same cover
- Choose the car for its insurance group. This is the big one and it is decided once, when you buy or lease. See choosing a dual-control car.
- Use a specialist broker and get three quotes. The market is small; the same risk is priced very differently by different insurers, and brokers know which one is keen this year.
- Join a trade body. The DIA and ADINJC negotiate member rates and bundle public liability, and the membership often costs less than the saving.
- Pay annually. Monthly instalments carry interest, typically adding 10% or more over the year.
- Declare everything. Not a saving, but the opposite of a loss: a refused claim on a dual-control car is a five-figure problem.
Insurance for a trainee
On a trainee licence you need the same cover as an ADI, bought as a PDI policy. It costs more, and some insurers will not quote a PDI at all, so start early. Most PDI policies convert to ADI cover on the same policy when you pass Part 3, without a new start date, which avoids a gap and usually brings the premium down at the next renewal. The stages of qualifying are in becoming a driving instructor.
The part-time question
If you teach ten hours a week, you still need a full instructor policy; there is no "occasional" cover, because the risk is the pupil, not the hours. What exists is a part-time rate from a few insurers, usually tied to a declared weekly maximum. If you grow past it, tell them. An insurer who finds a full-time diary behind a part-time policy has grounds to walk away from a claim.
Instructors covering the busier London boroughs, such as Islington and Camden, pay the most for cover and have the most to gain from a low-group car. Instructors in Havering and the outer boroughs sit closer to the national figure.
Premium ranges are those brokers and comparison guides quote at the time of writing and move every year; get your own quotes before budgeting. Nothing here is financial advice.